A Business Line of Credit that Moves at Your Speed

Draw the money you need, when you need it. Only pay for what you use. Porter’s Line of Credit combines fast decisions with a team that really looks at your business.

35+ years in business | over $10B funded

$50-250k Funding

Revolving credit line built for growing businesses.

12-Month Terms

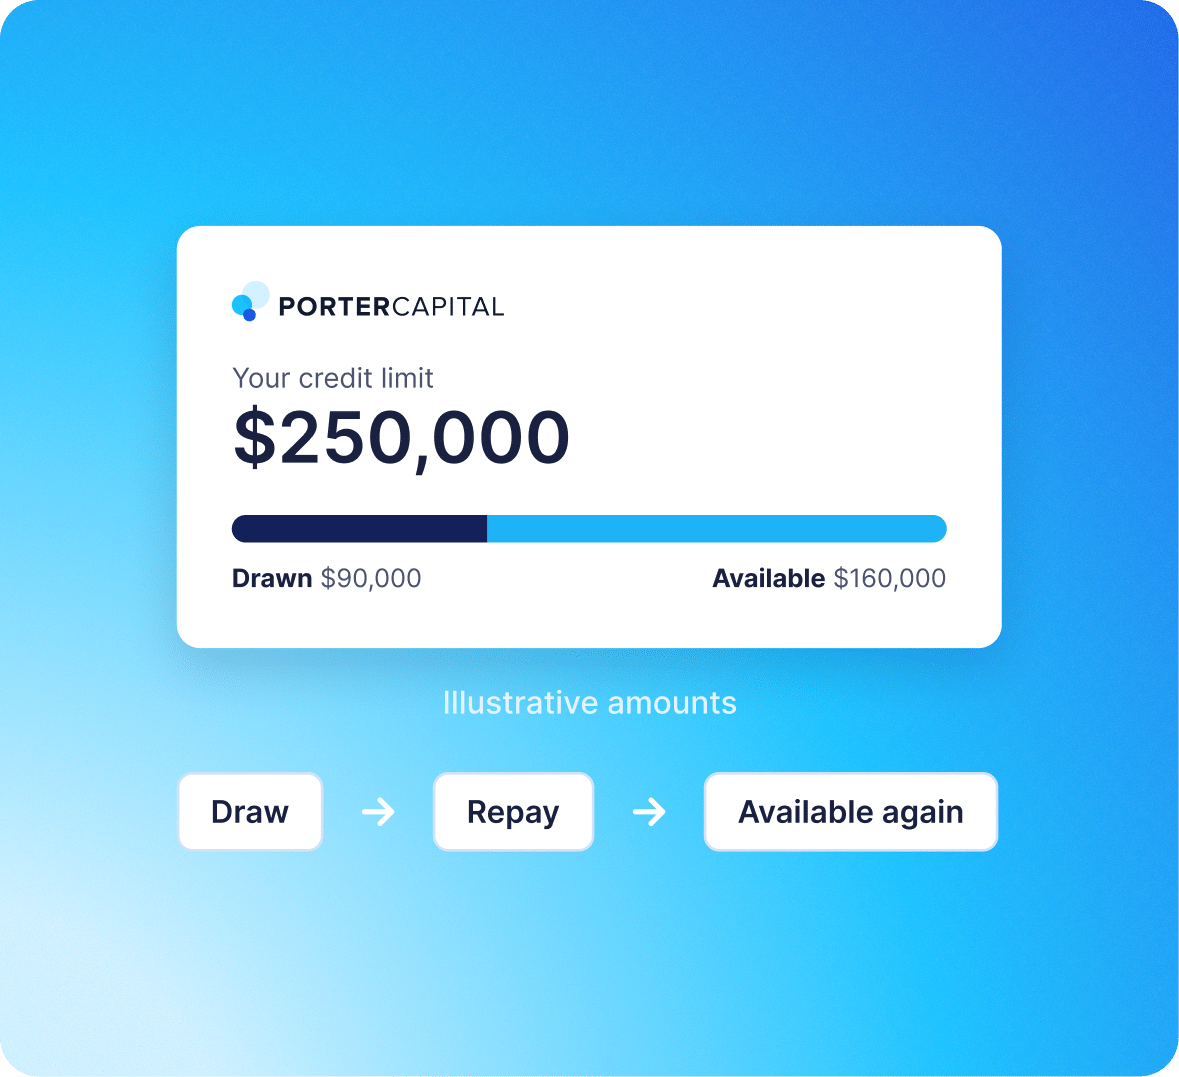
Draw, repay, repeat. No new application needed.

Human Underwriting

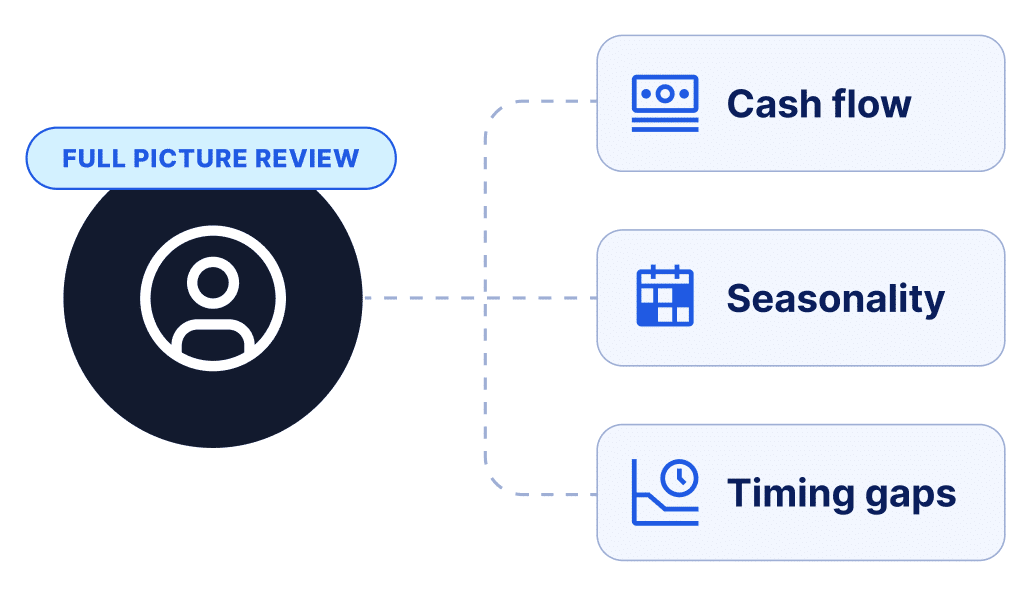
A real person reviews your business.

BUSINESS LINE OF CREDIT

What Is a Business Line of Credit?

A business line of credit gives you access to a pre-set amount of capital that you can draw from whenever you need it. It works similarly to a credit card but is built for business-scale expenses. You are approved for a credit limit, and from there, the money is yours to use as your cash flow requires. Pay down the amount you draw, and that capital becomes available again.

While traditional banks want years of financial history and a high credit score before they even take the meeting, Porter looks at the business you are actually running, not just the one on paper years ago. With us, if you are underbanked or a young company, you might qualify even if you heard “no” before.

A line of credit with Porter Capital is secured against blanket business assets, and our credit limits range from $50,000 to $250,000, with a 12-month revolving term.
Fast Process

Receive a term sheet the same day.

Same Day Approval

Your line is ready to draw within 24 hours of approval.

Predictable Payments

No hidden fees or unexpected charges.

BUSINESS LINE OF CREDIT

Why Businesses Choose Porter

Underwriting That Looks Past the Score

Automated lenders analyze fixed parameters and stop there. Porter’s team reads your actual cash flow, the seasonality, the timing gaps, and what is driving your numbers monthly. We understand your business’s current state, so a hard quarter or a thin file doesn’t close the door before the conversation even starts.

Built for Businesses Banks Pass On

If a bank wanted more history or a cleaner credit file than your business has now, you are exactly who this line of credit is for. You shouldn’t have to choose between “not established enough for a bank” and paying merchant cash advance rates just to keep cash flowing.

Capital That Doesn’t Cost More for Flexibility

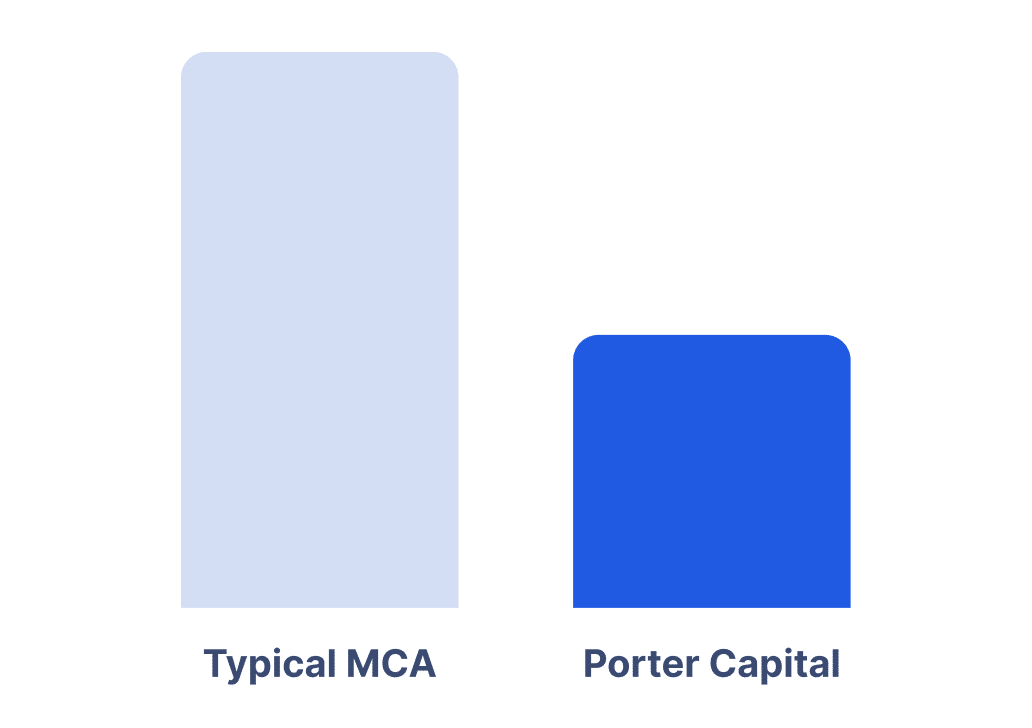
Revolving credit from short-term lenders or merchant cash advances often charges a premium for being available on demand. Porter prices its revolving credit line to stay meaningfully below that markup, so flexibility doesn’t come with a tax.

A Funding Specialist, Not a Call Queue

Your line is managed by people who really know your business and file, backed by a company with 35+ years in the industry and more than $10 Billion funded.

Draw What You Need, When You Need It

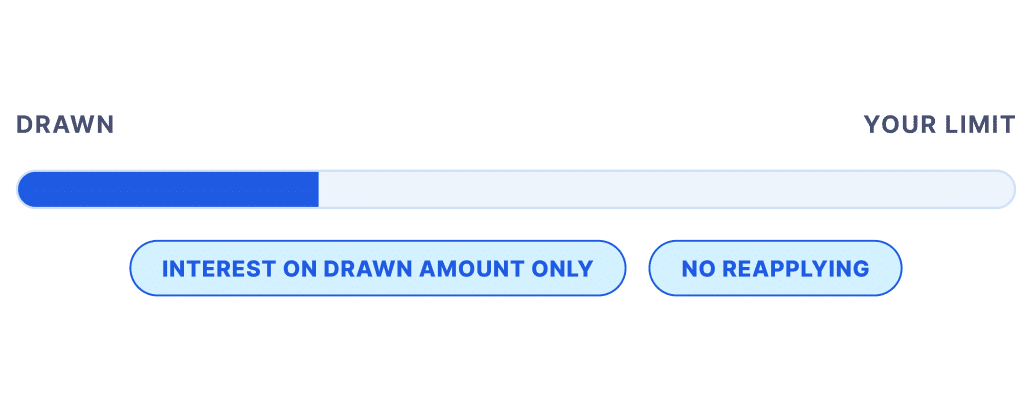
Don’t pay interest on the full limit the moment it’s approved, only on what you actually draw, when you draw it. Repay it, and that’s capital available again without needing a new application.

BUSINESS LINE OF CREDIT

Get The Best Out of Your Business Line of Credit

From leveraging opportunities to planning short term expenses, make the most out of this quick working capital.
Smooth Payroll and Vendor Timing

Cover the gap between when bills are due and when invoices are actually paid.

Stock Up Before a Busy Season

Buy inventory or materials ahead of demand without affecting your operating cash.

Take On Bigger Projects

Front the costs of a new contract or client before the revenue lands.

Cover Unexpected Expenses

Equipment breaks, opportunities show up, and a line of credit takes care of it.

Keep a Safety Net

Some businesses draw on it; most just like knowing it’s there.

BUSINESS LINE OF CREDIT

How It Works

01. Apply

Fill out a short online application. Find out if you were approved on the same day.

02. Talk to an Underwriter

A Porter funding specialist will review your business and guide you through options in an actual conversation.

03. Receive Your Funds

Once approved, your credit line is ready. Draw what you need, when you need it, and repay on a schedule built around your cash flow.

BUSINESS LINE OF CREDIT

Is a Line of Credit for Small Businesses Right for Me?

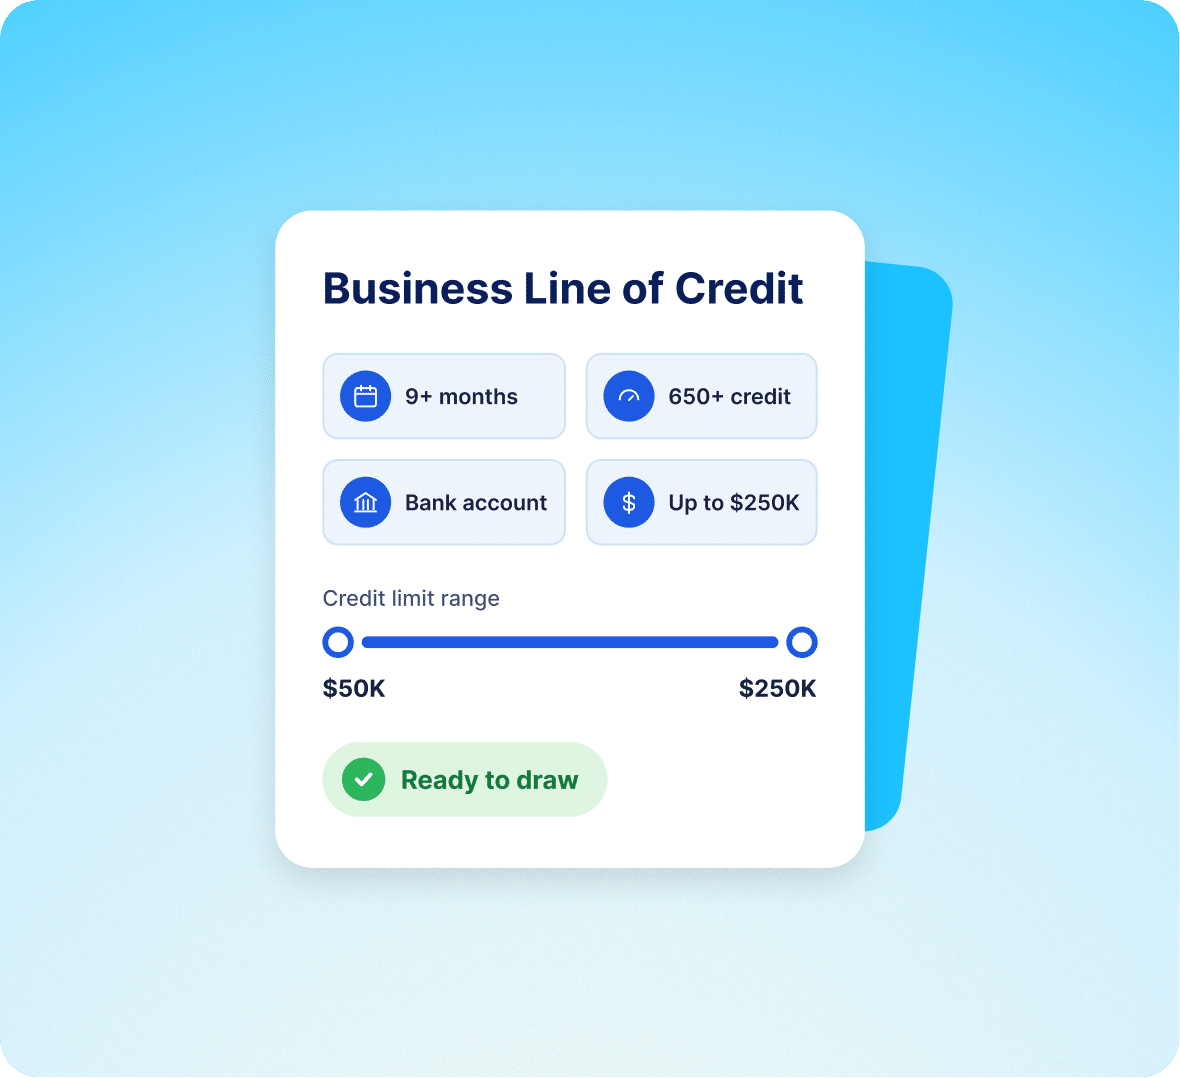
These are our must-haves:

  • 9+ Months in Business

  • 650+ Credit Score

  • Business Bank Account Required

  • $50K-$250K Credit Limit Range

Checked all the boxes?

Business Line of Credit FAQs

What to know about a line of credit, qualifying, and repayment before you talk to our team.

A business line of credit is revolving financing that lets you draw funds up to an approved limit, repay what you used and draw again, without reapplying. You only pay interest on the amount you’ve actually drawn, not the full limit.

A line of credit is revolving and flexible, while a term loan pays one lump sum upfront, with a fixed payment schedule. A line of credit works best for ongoing or unpredictable expenses, while a term loan fits large, planned costs.

Porter offers business lines of credit from $50,000 to $250,000, based on your business’s cash flow, profile and time in operation. Our team individually assesses your financials, offering a tailored number for what you need.

Porter looks for at least 9 months in business, a personal credit score of 650 or higher, and an active business bank account. Your file is reviewed individually, so not having one of the requirements isn’t a disqualifying factor.

Porter’s online application only takes minutes, and our funding specialists usually reach out on the same day. Once you are approved, you can get the line set up in 24 hours.

Applying will not affect your credit score until you accept the terms of the preliminary approval. Then, we will pull a hard credit check prior to providing loan documents. This is standard procedure with a loan.

Yes, Porter Capital will require a first lien on business assets. Porter Capital can work to pay off other lenders and release existing liens as part of the closing process and looks to have appropriately margined collateral for the loan. Porter Capital does not typically require real estate or outside personal assets to be pledged as collateral.

Porter Capital typically requires anyone who owns more than 20% of the borrowing business to guarantee the loan.

Get the Right Funding Alternative for Your Business

Tell us about your business and a funding specialist will walk you through the best options to access quick working capital.